Start with a real budget, not a payment
The biggest mistake I see first-time buyers make in Lebanon is shopping the monthly payment instead of the total cost of ownership. A $250/month payment sounds fine until you add PA registration ($45/year), title fee ($67), plate transfer ($11), sales tax, full-coverage insurance ($120–$180/month for a new driver here), gas, oil changes, and the annual PA state safety inspection ($20–$40 depending on where you go, plus emissions in most Lebanon County ZIPs). Realistic total monthly cost on a $12,000 used SUV is usually $520–$640 all-in.
A working rule I give every first-time buyer: your car payment plus insurance shouldn't cross 15% of your take-home. If you bring home $2,800/month working at Bayer, Hershey, WellSpan, or one of the warehouses off Route 422, keep total car costs under $420 — payment closer to $250. That leaves room for the surprise stuff (a battery, a set of tires, a $180 brake job) that will happen in year one.
Put together three numbers before you shop: max monthly payment, max down payment, and target total price. Bring them with you. If a salesperson shifts the conversation to "what payment can you handle" without talking price, slow down and steer back to the total.
Rule of thumb we use at Hunt Auto: if the total sale price divided by 60 gives you a payment your budget can't survive without stress, the car is wrong for you — not the loan.
Pick a first car that won't punish you in year two
The used car you buy at 22 sets the pattern for how you feel about car ownership at 30. Pick a bulletproof one and it will pay you back for the next five years. Pick a project and you'll be replacing tires, brakes, and control arms while you're still making payments.
For a first-time buyer in Central PA, I recommend sticking to what I call the reliable four:
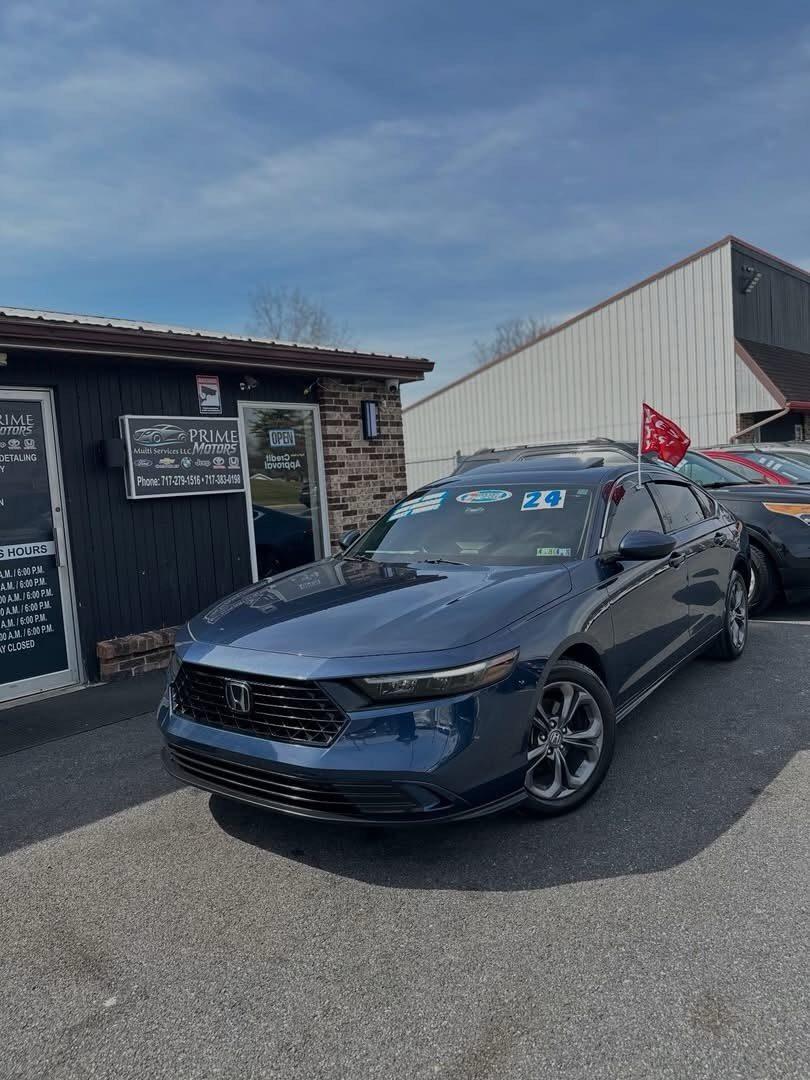
- Honda Civic / Accord / CR-V — parts are cheap, every mechanic in Lebanon knows them, and they routinely run past 200,000 miles.
- Toyota Corolla / Camry / RAV4 — same story. Boring is a feature.
- Mazda 3 / CX-5 — a step nicer inside for close to the same money, reliability nearly matches Toyota.
- Subaru Impreza / Forester — AWD makes real sense for Central PA winters between Blue Mountain and I-81; just budget for a head-gasket check on anything pre-2013.
What to avoid your first time around: European luxury out of warranty (a five-year-old BMW or Audi is a lifestyle, not a car), turbocharged performance trims, anything modified, and anything with a rebuilt/salvage title. Save the fun car for round two. See what we currently have in our Lebanon inventory — most of what we stock falls in the reliable-four zone on purpose.
Understand your credit before anyone pulls it
Most first-time buyers have thin credit — a couple of credit cards, maybe a student loan, no auto history. That's not a dead end. Lenders that work with dealerships in Central PA (lenders in our network and the national subprime banks) specifically program for first-time buyers; the trade-off is usually a higher APR and a required down payment.
Before you walk into any dealership, pull your own credit for free at annualcreditreport.com — this is the only federally authorized free source and it will not ding your score. You want to know your FICO score (any credit card app will show it now) and see what's on your report. Fix anything that's flat-out wrong before applying. If your score is under 620 and you have time, pay down a card or two — dropping utilization below 30% can bump your score 20–40 points in one cycle.
When you're ready, apply online. A single dealership application usually shops multiple lenders and shows up as one hard pull. Multiple applications within a 14-day window count as one for auto loans under most FICO models, so don't panic if a couple of banks look at you. You can start the process on our financing page and see options in about five minutes.
Where credit unions beat dealer financing
If you have a decent score (650+) and time, walk into lenders in our network on Cumberland Street or lenders in our network on Route 422 first. Credit union APRs on used autos have been running 1.5–3 points below what a dealer's captive lender will offer for the same credit. Get a pre-approval letter, then let the dealer try to beat it. If they can, take theirs. If they can't, use yours. Either way you win.
Bring the right documents on day one
You'll save hours if you show up ready. For a first-time buyer purchase at Hunt Auto Group in Lebanon, bring:
- Valid PA driver's license (or your out-of-state license if you're still in the 60-day transfer window PennDOT gives new residents).
- Proof of income — last two pay stubs, or three months of bank statements if you're self-employed or paid in cash. First-time programs almost always want to see income directly, not just an "I make $X" answer.
- Proof of residence — a utility bill, lease, or bank statement in your name from the last 60 days at your current address.
- Proof of insurance — you can bind coverage same-day by phone. Erie (headquartered in PA and cheap around Lebanon), State Farm, and GEICO are all fast. Call before you sit down; the finance office can't hand you keys without a policy number.
- Down payment — cashier's check, debit card, or ACH. Cash is fine up to $10,000 but the dealer has to file a Form 8300 with the IRS above that, so it slows things down.
- Two references — first-time buyer programs almost always ask. Give people who actually know you and will answer the phone.
- Your driver's license number and Social Security number memorized — every credit app asks. Not having them slows you down by 15 minutes.
Your exact rate and payment depend on your credit profile and the lender that approves you - ask our finance team for real numbers on a specific vehicle rather than relying on an example here.
Inspect the car — or bring someone who can
Every vehicle at Hunt Auto Group is inspected and CARFAX-verified before it's listed, but you should still do your own walk-around. Look for: uneven paint (repaint from body work — the passenger front fender is the most commonly replaced panel), tire wear pattern (a car that pulls has uneven wear on the front tires), oil at the tailpipe (light dust is fine, wet oil is not), and coolant color under the cap (should be bright green, pink, or orange — never brown). Start the car cold and listen for the first 30 seconds — a hydraulic lifter tick that fades is normal, tick that stays is not.
Take it on a real test drive: highway (Route 422 east toward Hershey or I-81 north out of Lebanon both work) plus a rough surface (some of the older 8th Street or Cumberland Street patches do the job). Turn the radio off. Feel the brakes at 40 mph — no shudder means the rotors are true. Then take one hard right and one hard left in a parking lot; clunks from the front end are usually control-arm bushings or sway-bar links, and those add up.
If any of this makes you nervous, ask us for the CARFAX and take the vehicle to an independent shop like Kauffman's Auto Service or Speedy Diesel in Lebanon for a full pre-purchase inspection ($60–$100). We say yes to those every time. A dealer that says no to a PPI is telling you something about the car.
The PA paperwork nobody explains
Pennsylvania makes registration easy but there are five documents that always come up in the F&I office:
- Form MV-4ST — the vehicle sales tax and registration application. The dealer fills it out; you sign. This is where the 6% sales tax gets calculated (on the sale price minus your trade-in — that's the PA tax break most first-timers don't know about).
- Title assignment — the back of the title is signed over to you. Notarization is required in PA for every private sale; dealers use a certified PennDOT agent on staff, so you don't have to hunt for a notary.
- Form MV-13ST — used when a family member gifts you the vehicle or when the transaction is exempt from sales tax. Rarely applies to a first buy, but ask if a parent is helping.
- Federal odometer statement — you verify the mileage matches the odometer. Never sign this if the number is off.
- PA damage disclosure — required in PA for any known damage over $500 or 25% of pre-damage value. Read it.
- Federal Buyers Guide — the window sticker on every used car. Tells you if the vehicle is sold "as-is" or with a warranty. Read this before you sign anything else.
Registration and title are typically issued to you within 30 days by mail from PennDOT in Harrisburg. You'll get a temp tag same day, good for 90 days. If you're transferring a plate from a car you already own, bring the plate and the current registration card — it saves you the $45 new-plate fee.
The traps the finance office will set (politely)
The F&I office (the desk after the salesperson) is where most first-time buyers overpay by $1,500–$4,000 without realizing it. The car is already priced. What happens next is add-ons. Some are legitimate, most are pure margin. Know them going in:
- GAP insurance — covers the gap between what you owe and what insurance pays if totaled. Can be worth it on a small-down loan, but dealer GAP averages $700–$900; your credit union sells it for $250–$400.
- Extended service contracts — a good one on a reliable used car can be smart; a $3,000 contract on a car that never breaks is not. Get the actual contract, read exclusions, verify the administrator (Endurance, CNA, GWC are legitimate).
- Paint and fabric protection — a $30 spray-on package sold for $499. Skip.
- Nitrogen tire fill — it's air, mostly. Skip.
- VIN etching — a $200 line item for something worth $25.
You can say no to any of these without losing the deal on the car. Practice the sentence "I appreciate the offer but I'm going to pass on the add-ons" before you arrive. It's easier when it's already in your mouth.
Ready when you are
First-time buying should feel like an upgrade, not a trap. Come in, look at the cars, ask any question, and walk out with real numbers. Call or text (717) 673-1484 to set up a visit, or apply online in about five minutes to see what you qualify for before you even come by. Se habla español, and we've been through this walk with hundreds of Lebanon-area first-time buyers — we'll take you through it at whatever pace you need.